Home Blog Page 96

NAAMSA – Comment On The December 2016 Monthly Sales, Calendar 2016 New Vehicle Sales Statistics And Prospects For 2017

Industry domestic sales ended 2016 on a weak note with aggregate industry new vehicle sales for December, 2016 at 41 639 units recording a decline of 7 519 vehicles or a fall of 15.3% compared to the total new vehicle sales of 49 158 units during the corresponding month of December, 2015. The December, 2016 new passenger car market and light commercial vehicle market reflected a year on year volume change of -14.0% in the case of cars and -17.8% in the case of light commercial vehicles. Sales of medium and heavy commercial vehicles declined by 18.2% year on year. 

In contrast, export sales had recorded an improvement in December, 2016 and at 18 668 units reflected a gain of 1 222 vehicles or 7.0% compared to the 17 446 vehicles exported during December, 2015.

Another challenging year with lower domestic sales offset by continued growth in vehicle exports 

For the third year in succession, new vehicle sales during 2016 in South Africa recorded a year on year decline. The slowdown in the domestic economy, above average new vehicle inflationary pressures, increases in interest rates, pressure on consumers’ and household disposable income and low levels of consumer confidence had contributed to a double digit decline in annual domestic sales volumes. In the event, aggregate sales during 2016 fell by 11.4% in volume terms to 547 442 units compared to the sales total of 617 648 in 2015.

Overall, 2016 turned out to be another extremely difficult year for the South African automotive industry with domestic new vehicle sales progressively under pressure, particularly at dealer level, despite attractive sales incentives and a strong contribution by the car rental sector which accounted for an estimated 16.3% of new car sales during the year. Industry trading conditions had remained intensely competitive characterized by pressure on dealer margins. Preliminary estimates of 2016 motor industry new vehicle related sales turnover indicated a decline of about 2.0%, taking account of sales volumes, changes in mix and a weighted average estimated increase of about 14.0% in new vehicle prices – to reach about R233 billion for the year. Industry new vehicle export sales were estimated to have added a further R105 billion to total Industry 2016 revenue.

2016 Vehicle exports represented the highest annual Industry export figure on record and total vehicle exports at 344 822 units were up on the 333 847 vehicles exported in 2015.

Assuming further improvement in the global economy – industry export sales during 2017 could improve by some 30 000 vehicles or about 10.0% to reach a conservative projection of 375 000 export units.

In summary, the decline in domestic sales was offset to a limited extent by continued growth in vehicle exports which in turn assisted in sustaining utilization capacities and employment levels of vehicle manufacturers.

Industry prospects for 2017 

Modest improvement in domestic new vehicle sales during the second half of the year together with further relatively strong growth in vehicle exports 

2017 is expected to be another difficult year for the domestic SA auto industry, however, a modest improvement in new vehicle sales is expected during the second half of 2017.

Annual aggregate annual industry sales by sector, since 2010, were as follows – 

[wpsm_comparison_table id=”4″ class=””]

Source: Lightstone Auto, NAAMSA

2016 Industry export sales data, compared to previous six years, were as follows – 

[wpsm_comparison_table id=”5″ class=””]

Source: Lightstone Auto, NAAMSA

The outlook for 2017 in terms of Industry domestic vehicle sales by sector is summarised hereunder – 

[wpsm_comparison_table id=”6″ class=””]

Industry production levels, on the back of expected further growth in vehicle exports, should however remain in an upward phase.

At this juncture, 2017 projections for South Africa reflect an expected improvement in GDP growth to around 1.5% (from 0.4% in 2016), in gross domestic expenditure to over 2.0% (from -0.3% in 2016), in growth in private consumption expenditure to about 2.0% (from 0.8% in 2016) and in fixed investment to around 2.2% (from -2.5% in 2016). Improvement in growth prospects is premised on the easing in drought conditions, the improvement in commodity prices, a decline in inflationary pressures on the back of a stronger Rand as well as recent improvements in the Purchasing Managers’ indexes and the Reserve Bank’s leading indicator. On the negative side, domestically, elevated political tensions are likely to continue to weigh on business confidence and the expected increase in taxes in this years’ budget will erode real purchasing power.

Internationally, volatile and uncertain conditions are likely to prevail during 2017. Elevated geo-political tensions and political uncertainty in major advanced economies associated with elections could heighten global risk aversion and trigger confidence shocks. Despite these considerations, the global economic outlook at this stage, remains positive and should continue to lend support to South Africa’s improving vehicle export performance. Ultimately, industry vehicle exports would remain a function of the performance and direction of global markets. Vehicle exports to Europe, Australasia, the United States, Asia and South America were expected to show further upward momentum.

The general expectation in the industry was that domestic new vehicle sales would remain fairly flat going into 2017. NAAMSA remained hopeful, however, that on the back of the expected improvement in key economic indicators, domestic sales would regain some traction in the second half of 2017 with year over year growth perhaps settling in the 2.5% to 3.5% range and hold to around that level going forward.

Factoring in the expected improvement in exports, domestic production of motor vehicles in South Africa was expected to show an increase from 604 000 vehicles produced in 2016 to close on 641 000 vehicles in 2017 – an improvement in vehicle production of about 6.0%. This figure could prove conservative if vehicle exports expand more than currently anticipated.

The projected higher vehicle production was consistent with the official vision for the Industry which is to remain a premier supplier of high quality, competitive automotive original equipment parts and accessories and vehicles to international markets and in the process, to achieve an annual domestic vehicle production figure of close to 850 000 vehicles by 2020.

Internationally and domestically, vehicle manufacturers would continue to focus on new models and products through sustained investment and new technologies. Technologies such as artificial intelligence could begin to reflect a tangible impact across sectors. Autonomous vehicles and driver assisted automatic systems as well as increased use of information technology in vehicles were likely to feature in the future.
Mercedes-Benz Vans Invests In Starship Technologies

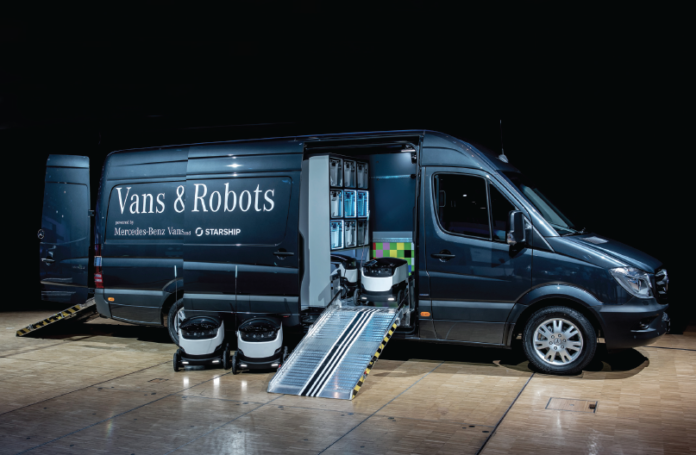
The two companies already introduced the so-called mothership concept back in September 2016. The concept combines the advantages of a van with those of an autonomous delivery robot. A Sprinter presented as a prototype serves as a mobile loading and transport hub for eight robots.

Thanks to the intelligent interlinking of delivery processes, it will play a part in significantly improving the efficiency of last-mile delivery logistics in future. The mothership concept is the first outcome of a research and development cooperation between Mercedes-Benz Vans and Starship Technologies that began in 2016. Through its financial commitment to Starship Technologies, Mercedes-Benz Vans is now reinforcing this strategic, long-term collaboration.

“The robot can only travel short distances under its own power and until now has had to return to the warehouse to be reloaded after each delivery. On the one hand, the introduction of the van as a mobile hub widens the operational radius of the robots significantly, while also rendering superfluous the cost-intensive construction and operation of decentralized warehouses. We see the combination of these two technologies as an opportunity to give our van customers access to some completely new services and business models. At the same time, we make the delivery process much more convenient for the end customer”, says Volker Mornhinweg, Head of Mercedes-Benz Vans. “For example, the concept makes it much easier to deliver goods to the end customer on time.”
Systematic development 

The aim is to develop the concept systematically over the coming months. As the two companies recently announced at CES 2017 in Las Vegas, initial pilot tests for this combination of van and robot are planned for Europe. Following pilot testing of the delivery robots, which has been and continues to be undertaken by Starship Technologies with other partners, the plan is to begin widespread testing of the joint concept with one or several logistics partners. The launch of the pilot project in a real-world environment is scheduled to take place later this year.

Mercedes-Benz Vans presses ahead with the transformation of the transport sector 

Mercedes-Benz Vans unveiled its strategic future initiative adVANce last September. The business division is systematically directing its focus at new, quickly changing customer needs, with a particular eye to identifying innovative solutions. The company will invest some 500 million euros in the advancement of digitization, automation and robotics in vans as well as in innovative mobility offerings until 2020. Mercedes-Benz Vans is thus evolving from a globally successful van manufacturer into a supplier of holistic system solutions.


GM Commits To 100 Percent Renewable Energy By 2050

General Motors plans to generate or source all electrical power for its 350 operations in 59 countries with 100 percent renewable energy — such as wind, sun and landfill gas by 2050.

“Establishing a 100 percent renewable energy goal helps us better serve society by reducing environmental impact,” said GM Chairman and CEO Mary Barra. “This pursuit of renewable energy benefits our customers and communities through cleaner air while strengthening our business through lower and more stable energy costs.”

This new renewable energy goal, along with the pursuit of electrified vehicles and efficient manufacturing, is part of the company’s overall approach to strengthening its business, improving communities and addressing climate change. GM is also joining RE100, a global collaborative initiative of businesses committed to 100 percent renewable electricity, working to increase demand for clean power.

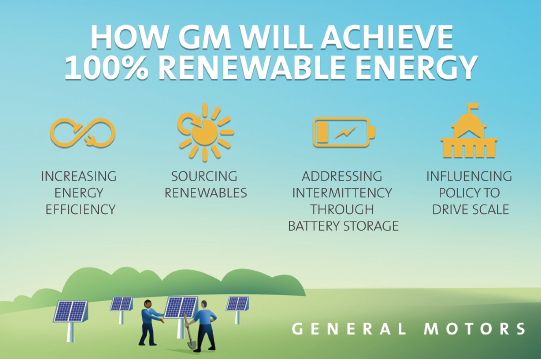
In 2015, GM required 9 terawatt hours of electricity to build its vehicles and power its offices, technical centers and warehouses around the world. To meet its new renewable energy goal, GM will continue to improve the energy efficiency of its operations while transitioning to clean sources for its power needs.

Today GM saves $5 million annually from using renewable energy, a number it anticipates will increase as more projects come online and the supply of renewable energy increases. In addition, the company anticipates costs to install and produce renewable energy will continue to decrease, resulting in more bottom-line returns.

The new renewable energy commitment builds on GM’s previous goal to promote the use of 125 megawatts of renewable energy by 2020. The company expects to exceed this when two new wind projects come online later this year to help power four manufacturing operations.

“This bold and ambitious commitment from General Motors will undoubtedly catch the attention of the global automotive industry,” said Amy Davidsen, North America executive director at The Climate Group. “GM has already saved millions of dollars by using renewable energy, and like any smart business that recognizes an investment opportunity, they want to seize it fully. We hope that through this leadership, other heavy manufacturing companies will be inspired to make the switch too.”

Scaling the commitment 

GM is in the process of adding 30 megawatts of solar arrays at two facilities in China. Its Jinqiao Cadillac assembly plant in Shanghai will feature 10 megawatts of rooftop solar and 20 megawatts of solar carports, which will cover 8,100 parking spaces at the company’s vehicle distribution center parking lot in Wuhan.

GM has pioneered the use of renewable energy for more than 20 years, saving $80 million to date. The company has 22 facilities with solar arrays, three sites using landfill gas and four that will soon benefit from wind. This experience will help GM scale renewable energy use to all facilities globally.

GM is in a unique position to meet this renewable energy goal given its electric vehicle battery expertise. Energy storage can ultimately address the intermittency or reliability of wind and solar energy. GM is now using Chevrolet Volt batteries for energy storage at its Milford Proving Ground data center office.

Collaborating to make renewable energy more accessible 

GM joins 69 companies that have made the RE100 pledge. As a founding member of the Renewable Energy Buyers Alliance and Business Renewable Center, and one of the first signatories of the Renewable Energy Buyers’ Principles, GM helps scale the availability and adoption of renewable energy. These organizations, spearheaded by the Rocky Mountain Institute, the World Wildlife Fund and the World Resources Institute, work to identify barriers to buying clean energy and develop solutions to meet the growing demand.

GM will continue to work with cities, policymakers, renewable energy developers, utilities, NGOs and other stakeholders on the transition to a clean-energy economy.

Volkswagen Inaugurates Vehicle Production Facility In Kenya

Volkswagen is forging ahead with the regionalization of its worldwide automobile business and recently inaugurated a vehicle production facility in Kenya. Together with the President of Kenya, H.E. Uhuru Kenyatta, Dr. Herbert Diess, CEO of the Volkswagen brand, was present when the first locally produced Polo Vivo rolled off the production line. With the CKD production of the bestselling car model in the sub-Saharan region, Volkswagen is stepping up its commitment to Africa. This is a key step in the development of new opportunity markets – with the right products, local partners and training in the region.

At the inauguration, Diess underlined Kenya’s key role within the Volkswagen brand’s Africa strategy, “Volkswagen is strengthening the production region of Africa and providing additional impetus for the further regionalization of the brand – as a reliable and responsible partner. This is symbolized by the first Polo Vivo produced – a car from Africa for Africa.” Diess also said, “here in Kenya, we will be producing cars that bear comparison with European quality standards. This is why we are opting for training and local skills in automobile production.”

In addition to vehicle production, Volkswagen will be offering Kenyan customers a comprehensive package including a manufacturer’s guarantee as well as a maintenance and service plan. Financing schemes will be developed together with local banks in order to allow individual mobility and to provide Volkswagen with the impetus it needs for its re-entry to the Kenyan market.

President Kenyatta said, “a few months ago, this was only a dream. Now Volkswagen’s investment in Kenya has become reality. This is further proof of my government’s determination to strengthen the production location of Nairobi and to forge ahead with the industrialization of the nation.”

Third Volkswagen production plant in Africa

The joint project implemented together with DT Dobie in Thika near to the Kenyan capital Nairobi is Volkswagen’s third production plant in Africa, together with one plant in South Africa and one in Nigeria. In the initial phase, annual production of up to 1,000 vehicles is planned. In the long term, it will be possible to produce up to 5,000 units per year at the plant of Kenya Vehicle Manufacturers (KVM). The assembly facility is flexibly designed and offers the possibility of investigating the production of further models in the event of positive developments in the new car market. In addition, the Volkswagen Group recently announced plans to start vehicle production in Algeria.

Volkswagen committed to sustainable training in Kenya

For the start of production at Thika, the employees are being trained by Volkswagen Group South Africa. This will ensure that all vehicles have constant high quality levels. Volkswagen is also investigating possible approaches for the establishment of a sustainable, practically oriented training initiative.

Apart from school or academic training, young people are also to receive practical training in order to improve their employment prospects in the region as a whole.

Kenya is an opportunity market in Africa. The country has an outstanding position within the region of East Africa and has the most powerful economy in the East African Community (EAC) with a GDP of about US$63 billion. In addition, Kenya is a key transit country for trade throughout East Africa. The good economic relations between Kenya and Germany are also being continuously and strategically expanded by the governments concerned.

Volkswagen and Kenya – this is a relationship with a tradition – Volkswagen already assembled the Beetle in Kenya in the 1960s. The Volkswagen brand is now returning to Kenya with its first model, the Polo Vivo.

Open House December 2016 Review

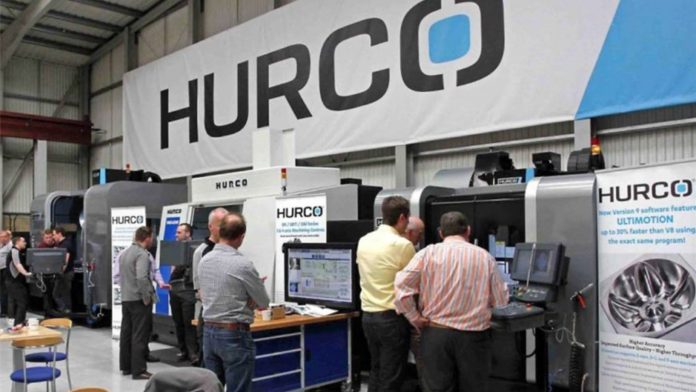
At its busy open house in High Wycombe during December 2016 and in the immediate aftermath, Hurco Europe took orders for 12 vertical machining centres to the value of £800,000. The company welcomed 70 engineers from 50 manufacturing companies from the OEM and subcontracting sectors during the two-day show.

The event cemented a solid start to the current financial year, beginning 1st November, since when over 70 orders have been booked, double the number compared with the same period last year.

Managing director David Waghorn said, “trading was quiet in the run-up to Brexit, but business has picked up strongly since late summer and it looks set to continue into 2017. Our 2015/16 turnover was just short of £20 million, the fifth successive year it has been very close to that figure.

“We launched our new, entry-level VM5i machining centre in September and sold 10 before our open house, which helped to boost turnover in both financial years.

“The proportion of new companies buying Hurco equipment in 2015/16 was just over 40 percent, similar to the last five years, which is the reason we have been able to sustain our business growth.”

A further explanation for the near-record level of trading last year was the sale of five German-built Roeders 5-axis machining centres with automation into the UK and Ireland under a sole agency agreement. Virtually all models in the Roeders machining centre range can be equipped with jig grinding at 90,000 rpm. The option is creating considerable interest presently in the motorsport and automotive sectors.

Sales of Hurco’s own 5-axis machining centres are also holding up well, with the VMX42SRTi and VMX60SRTi B-axis models with flush rotary table proving most popular, although trunnion-type configurations are preferred for some applications.

Hurco’s large, high-value DCX bridge-type machining centres have contributed well to the bottom line. Mr Waghorn advised that a 5-axis variant of the DCX32 is currently being installed and announced that a DCX62 with 6.2 metre X-axis is now available, built to order. There are over 20 DCX-series machines operational in the UK.

Another factor that raised turnover in 2016 was a propensity for customers to enhance their machine specification with, for example, extra rotary axes, higher spindle speeds, full swarf management, through-tool coolant and probing for parts and tools.

Hurco has been selling machining centres for the whole year with its latest MAX 5 control system, which has proved highly popular. Running the latest WinMAX 10 software, it is ideal for conversational programming of 5-sided and 4th axis rotary cutting cycles, but also handles all of the latest ISNC codes required to run simultaneous 5-axis programs.

Unlike previously, a customer can take delivery of a VM-series machining centre with a single-screen MAX control and upgrade it later to a twin-screen version with the addition of a hinged, 19-inch LCD screen, as supplied with VMX- and DCX-series machines. The operator can then view an image of the part as the cycle is being built up conversationally or monitor a machining process while the next job is being programmed.

Products and services from a larger number of partner companies than ever were promoted at the open house. They included workholding equipment suppliers 1st MTA and Roemheld, probing systems firm Renishaw, tooling suppliers Horn, Kyocera SGS, Dormer Pramet, Gewefa and Coventry Engineering, tool presetter company Zoller, CNC bar feed firm Hydrafeed, filtration equipment specialist Filtermist, CADCAM solution providers Autodesk, Edgecam and Open Mind, Erowa automation system agent REM Systems, Anotronic with its new River 3 EDM drill, Finance For Industry and Cromwell, a supplier of cutting tools, abrasives and power tools as well as products for factory maintenance and repair.

Data-Driven Business Models Are High On The Agenda Of European Machine Tool Builders

The CECIMO General Assembly in Rome recently confirmed that according to a CECIMO inquiry, data-driven business models are high on the agenda of European machine tool builders. Building a hybrid skills pipeline that merges ICT and production technologies is seen as an important priority too. Greater certainty on the right to access different types of data generated by machines would be a necessity for machine tool builders to tap into new business opportunities.

Filip Geerts, CECIMO Director General

European machine tool production is growing slightly to a level above 24,2 billion euro in 2016, while exports will remain stable this year at 18,7 billion euro, and the European machine tool production global market share is growing and exceeded 40% in 2016.

Results of the CECIMO inquiry on new business models by machine tool builders 

During its General Assembly Meetings, CECIMO conducted an inquiry with CEOs and owners of European machine tool companies. According to the inquiry for most of the companies that participated, data-driven business models will be the most prioritized over the next 10 years while other business models include services based on in-house knowledge, product-as-a-service, and platform-based.

Mr Luigi Galdabini, CECIMO President

Half of the machine tool builders questioned said that launching new education programmes in Europe that merge ICT and production technologies is the most important policy pillar to underpin new business models, followed by future-proof and technology neutral regulations.

The majority of machine tool builders find that understanding customers’ digital needs and cooperating with them are essential to develop new business models.

“Machine tool builders are increasingly facing difficulty in finding the workforce possessing the knowledge and skills needed to apply digital solutions in the field of advanced manufacturing. In order to tackle this pressing challenge, public authorities at national and regional levels as well as education providers together with industry should invest more in design and delivery of a new education approach merging various disciplines including software programming and production technologies. Secondly, we see that Member States are launching and implementing ambitious investment programmes in modernization of manufacturing and service-based business models. Nevertheless, the EU has an important role to play in the coordination and acceleration of such investment programmes. We can only cope with the competitive pressures arising from across the world by pooling our resources in Europe and coordinating our actions” states Mr Filip Geerts, CECIMO Director General.

Paving the way for a data-driven manufacturing sector in Europe 

Existing EU regulation on data have mainly focused on personal information protection and does not address the complexities of manufactures in B2B sectors. Currently, access to raw data generated by machines is generally defined by contracts between suppliers and users. Nevertheless, working with bilateral contracts in the future may be challenging as the amount and type of data collected are increasing and data-driven business models are likely to grow through industrial data platforms and networks.

Under this light, future-proof and technology-neutral key principles and greater certainty on the right to access different types of data generated by machines along the value chain are a necessity for industrial actors to tap into new business opportunities. “If Europe wants a competitive and data-driven industrial base, machine tool builders will need access to the data deriving from the machines used by various customers along the value chain. Clear benefits of this access include increased productivity, safety, energy and resource-efficiency for the entire European industry, taking into account the fact that machine tools are a key enabler of the production of other industrial equipment and machinery across various sectors” points out Mr Luigi Galdabini, CECIMO President.

Economic situation and outlook 

In spite of the global economy’s weakening growth and high levels of uncertainty in international trade relations, the European machine tool industry shows clear signs of strength. Machine tool production in Europe grows its global market share to exceed 40% in 2016.

Investment in modern manufacturing equipment remains relatively low, but the recovery of economic activity is visible and business confidence in Europe may support additional growth in investment. All economic indicators from the destination markets point to a stable growth momentum.

Global machine tool production will decrease slightly (2% – 3%) from 61.5 billion euro in 2015 to 60 billion in 2016. Brazil and China are reporting negative MT consumption and production with negative double digit figures. CECIMO estimates the European machine tool industry will defeat this trend and confirm the good results of 2015 by exporting again an amount of 18,7 billion euro. Exports to Asia are declining in line with local economic developments. Exports to Russia are heavily impacted (-30% yoy) by EU trade sanctions. Exports to the Americas are increasing due to investment into new or upgraded automotive plants in the US and Mexico. Then domestic European consumption is supported by a resilient investment climate in Europe with ongoing investments into more efficient production equipment.

In addition, growing digitisation efforts in the manufacturing sector makes the European machine tool offering increasingly attractive for foreign markets. On the domestic side, consumption and some previously postponed investments drive local machine tool sales. Despite a lagging global consumption trend, CECIMO is well prepared to keep its production above 24 billion euro and further grow its global market share.


Quality Assurance: “Random-Sample Measurements Often No Longer Suffice”

The German-language scientific periodical “Bild der Wissenschaft” has described Prof. Gisela Lanza as the 120-percent woman, because for four years she worked simultaneously as the first incumbent of the Shared Professorship of Global Production Engineering and Quality at the Karlsruhe Institute of Technology (KIT) and at the automaker Daimler. But how does such an active expert on global production systems assess the new, important role of metrology for quality assurance from the viewpoint of Industry 4.0 and the Industrial Internet of Things (IIoT)? 

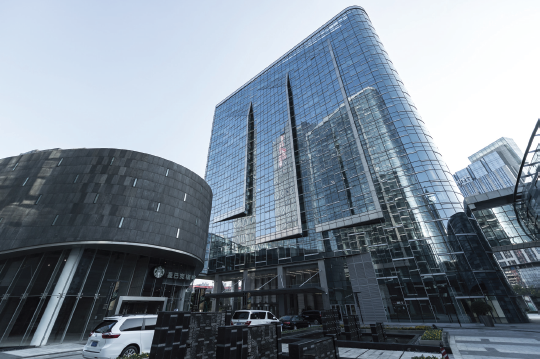
The Global Advanced Manufacturing Institute (GAMI) in Suzhou (China) with a current staff of 20. Gisela Lanza has headed the institute since 2009. Photo credit: KIT

Professor Lanza, how is Industry 4.0 influencing quality assurance and metrology? 

GL: Thanks to the increasingly important influence of sensor technology, we will definitely be able to collect very many more measured data, and thus improve our detection of causal connections. I would even venture the hypothesis that in future we will be recording 100 percent of all important measured values. 100-percent testing means quality data (meaning all critical parameters) will no longer be acquired by random sampling, but with 100-percent coverage. This signifies a radical change in quality control, because now we can get a whole lot closer to the tolerance limits.

What will in your opinion the quality control of the future look like? 

GL: I’m predicting intelligent, adaptive quality control strategies. One example here might be a revival of pairing strategies, which production people often hate because of the complicated mathematical approach and the logistical outlay involved. Here, components with different quality features are used in pairs, so as jointly to provide the functions of an assembly with very high tolerance requirements. Pairing strategies are an obvious option if not every component produced is any longer able to meet the specified tolerances. One example here is the injectors used in engines, which have to work with an operating pressure that in future may reach 3,000 bar. Rigorous deployment of inline metrology will here enable even more intelligent, component-specific pairings to be used in conjunction with dynamic modification of production parameters, which open up multifarious new options.

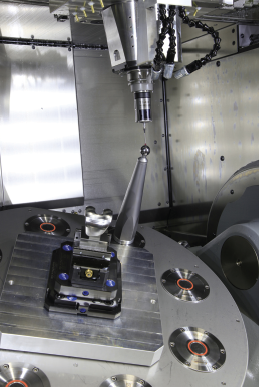
High-precision measurements: the workpiece scanning system is calibrated under program control, before the machine operator uses it to measure his workpiece with maximized accuracy. Photo credit: Heidenhain

So will data be increasingly acquired inside the production line? 

GL: Yes. There’s an ongoing trend towards more inline metrology, or even towards process-integrated measuring instruments, permitting minimized control loops. Measurements are no longer taken in a separate measuring room, but directly in the production process. This is increasing the demand for metrology applied in modularized mode in plants and production lines, while standard measuring instruments are less sought after. Metrology is turning into a project business, in which the customized application is the crucial competitive factor.

Talking of sensor integration – can a machine tool be converted into a measuring machine? 

GL: This goal has been around for some time and it continues to be a very exciting task. But there are still numerous challenges involved, such as high costs and interference factors from the production process like temperature or dirt. What’s more, typical metal-cutting parts often require a very high degree of measuring accuracy. Users also want an independent metrological framework, which ideally enables measurements to be taken in parallel to machining – this is known as concurrent measurement. Measuring with the machine tool, however, is nowadays already standard procedure for high-precision products. One example here is the production of diesel injectors at Bosch.

Wanted – intelligent evaluation of the huge data volumes involved 

When the machine tool and the production process are able to acquire more data with the aid of sensor technology: what does that mean for signal processing in regard to real-time capability? 

GL: In terms of technology, individual sensors are being replaced by distributed sensor networks, because a networked infrastructure is an essential precondition for using the potentials of inline measurements with maximized efficiency. Users want intelligent, interlinked evaluation of the data concerned. Experts here speak of a fusion of data from several different sensors, which lead to a combined metrological result. In order to explain the complex causal connections of a process, data mining algorithms such as neuronal networks are well suited. So the main consideration is that the meaningful data correlations need to be filtered out.

What role will quality data generated in the factory of tomorrow then play? Can the big-data volume thus created be meaningfully managed and mastered? 

GL: At present that’s still not easy to assess. The basic precondition here is a harmonized software architecture. Once this has been established as a basis with harmonized data structures and interfaces, I’m expecting it to be design-enhanced by a gradual increase in complexity – from data acquisition all the way through to adaptive, self-learning control loops.

How can the different worlds – meaning shop floor (the machine tool industry), networking (the web) plus hardware and software (metrology) be fruitfully reconciled? 

GL: Because the classical automation pyramid, from the process itself all the way up to the corporate level, is disappearing, cross-level information interchange is essential. In this context, the Manufacturing Execution System (MES) operating close to the process is gaining steadily in perceived importance. Unfortunately, you see, it would appear impossible in the next few years to directly utilise and evaluate the data from sensors without an MES. What’s more, we need harmonised interface standards like OPC/ UA, a standard that is currently gaining wide acceptance for automation technology.

But the alleged necessity for real-time control now appears to be hampering progress a bit – so does everything really have to be run in real-time? 

GL: No. Then there’ll just be three non-conforming parts until then as from Number Four I’m once again manufacturing specification-compliant parts.

Can you cite an example of best practice? 

GL: I see the Bosch Group as a leading key user, embracing full-coverage, harmonized use of its own MES and IoT software, which it also sells as a key vendor, so as to link up process, measured and order data (IoT: Internet of Things).

China, in particular, is catching up 

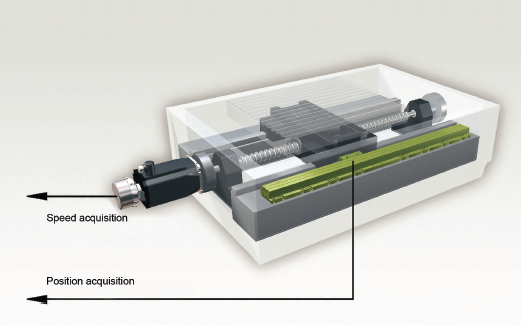
Encapsulated length measuring instruments: a closed-loop control renders position measurement in the machine tool independent of thermal and other influences from the ball screw drive. Photo credit: Heidenhain

You’re also familiar with global production strategies – where are there international differences in terms of quality assurance? 

GL: In what are called the emerging markets, meaning the present-day low-cost nations, testing is still often being performed in the traditional manner at the end of the process chain. But the sheer speed of change here is breath-taking – in China, particularly, there is enormous receptiveness for Industry 4.0. The predominant attitude there is – if I’m investing, then I’m going to spend my money on the very latest technology.

Talking of China – as the Director of the Global Advanced Manufacturing Institute (GAMI) in Suzhou you’ve also had a good look at the quality assurance operations there. What differentiates the strategies of the Chinese production facilities from those of Europe’s industrial sector? 

GL: In Europe, the dominant category is the older brownfield plants, which equip their existing lines with sensor technology. In China, there’s a major trend towards new greenfield plants, which fit their new lines with large amounts of immanent sensor technology. I’m observing in China a readiness to make very substantial investments in Industry 4.0. They are spending a whole lot of money on hardware – often in conjunction with automation. However, I see this as problematic, because Industry 4.0 and the requisite system competence are not things you can buy. After all, what use is even the best of measuring machines to me if I don’t understand the system involved? It’s auspicious for China though that the significantly younger workforces there are much more receptive to IT applications. But often, there’s still a lack of basic comprehension of how control loops actually work.

Later this year, EMO will be held in Hannover – what role does this fair play for you and your staff? 

GL: As a specialist in production technology, I shall anyway be going to EMO 2017. But because metrology is increasingly being integrated into the processes and machines involved and production technology is merging with metrology, it is becoming progressively more relevant for metrologists as such. In this context, by the way, I was also gratified to note the Quality Area at METAV 2016. This is the right approach, true to the motto of Get out of the test room and into the production line.


EMO Hannover 2017 Heading For Record

Just under a year before the fair begins, the figures for official registration at EMO Hannover 2017 are looking rather impressive – more than 1,700 firms from 40 different countries have registered for the world’s most important trade fair for the metalworking sector, booking a stand area totalling 152,000 square metres for the period from 18 to 23 September 2017 in Hanover. This means the current registration status lies significantly above the comparable result of the previous event. “It looks very much as if EMO Hannover 2017 will end up with a record number of exhibitors,” declares EMO General Commissioner Carl Martin Welcker. 

Carl Martin Welcker, General Commissioner of the EMO Hannover 2017.

The reasons he cites for the substantial rise are firstly that after four years EMO is returning to Hanover, the venue that ever since the first event in the 1970s has been acknowledged as an international sectoral highlight and a superlative platform for showcasing innovations. Secondly, the early-booker offer presented to the exhibitors for the first time has taken full effect. It has already produced a definite plus in terms of area and the number of exhibitors, explains EMO’s General Commissioner. Not only have German manufacturers registered for sizeable stands, but more especially Asian companies too. They have once again increased their areas in comparison to the previous event, a development that’s been observable for years now. Overall, Asia currently accounts for more than a fifth of EMO’s exhibitors.

Under the motto of Connecting systems for intelligent production, the world’s upcoming premier trade fair for the metalworking sector focuses fruitfully on the megatrend of digitization and networking under the aegis of Industry 4.0. To quote Carl Martin Welcker, “with our new motto, we’ve certainly hit the bulls-eye with our exhibitors. Numerous firms can identify with this slogan, and will be showcasing their solutions in the field of Industry 4.0 either on their own stands or in the Industry 4.0 Area”. This, believes EMO’s General Commissioner, has created the optimum foundation for progressing the success story generated by former events in Hannover.


Turning: Making All The Right ‘Turns’

However, Craft Machine Tools is aware that even in this digital age of ever changing technology there is still a need for the traditional conventional lathe. Given this understanding, Craft Machine Tools offer both, a comprehensive range of CNC – and conventional turning products from Taiwanese based Feeler, a member of the Fair Friend Group.

Feeler enjoys a worldwide reputation for product excellence and reliability. This success is the result of their innovative design, in-house manufacturing capabilities and rigorous quality control.

As testimony to this success Feeler have received numerous awards including being named in Taiwan’s Top 100 Brands; add to this Machine Tool Industry Awards for Excellence in Research and Innovation in 2011.

The Best Quality and Service Machine Tool Manufacturer from Taiwan (by Asia Pacific Equipment News) and a double award for National Quality and National Award of Excellence.

Feeler offers a comprehensive range of CNC turning centers, including but not limited to:

For companies interested in purchasing a conventional lathe at competitive prices and without sacrificing quality and precision, Craft Machine Tools offer a high speed precision lathe with inverter transmission. The Craft conventional lathe is in a class of its own boasting features such as selective bed widths of 300mm, 350mm or 400mm.Varied spindle bore diameters of 58mm, 80mm, 85mm and 120mm, added protection to the shaft and gears in the headstock, thermal treated and precision ground alloy gears, overload device to ensure safety when operating, wear-resistant phosphor bronze lead screw nuts, thermal treated Meehanite bed casting and a one-piece base for high rigidity and low vibration.

Craft Machine Tools have extended their offering to cater for those looking for larger conventional lathes and have partnered with renowned Chinese’s manufacturers Dalian Machine Tools and Gongtao Machine Tools.

All conventional lathes supplied by Craft Machine Tools come complete with a 3 and 4 Jaw Chuck, DRO, rapid traverse, work light, coolant system, steadies, tool kit and an oil gun.

On the purchase of a machine tool from Craft Machine Tools, your purchase includes commissioning and training.

[wpsm_comparison_table id=”1″ class=””] [wpsm_comparison_table id=”2″ class=””] [wpsm_comparison_table id=”3″ class=””]


For more information, contact Craft Machine Tools – Tel: (011) 845-2030.

Turning: Hurco CNC Lathe Considerations And Terminology

I am often amazed at the number of highly skilled CNC machinists and operators who can accomplish almost anything on a milling machine, but who are very uneasy and intimidated around a lathe because they don’t really understand the meaning of basic lathe terminology.

Michael Cope, Senior Applications Engineer & Product Specialist at Hurco Companies, Inc.

That is the purpose of this article. I will try to clarify the meaning and benefit of a few of the “not-so-obvious” features that exist on a typical lathe spec sheet, and attempt to clarify their definition and explain why they might be an important consideration when purchasing a CNC lathe.

Maximum Turning Diameter: This simply indicates the largest size of part that can be turned on the machine – using standard length tooling – without interference or collision with guarding or other machine components.

With the X-axis retracted all the way positive, what size of part can be turned safely, as it relates to X-axis travels of the machine tool. For example: if you are looking at a machine with a max turning diameter of 16″, and the parts that you run on a regular basis are 15″ in diameter or larger, then you would probably want to look at a machine with a larger maximum turning diameter.

Even though, in our example above, the part would technically “fit” in this case, you must realize that you are running on the very edge of the envelope, and if you had to hang a tool out of the turret farther than normal – for one reason or another – you would likely NOT have enough X-axis travel to accommodate the part.

Maximum Swing: Refers to the largest diameter part that can be spun in the chuck without mechanical interference with guarding, cross-slide, or other machine components located near the chucking area. Depending on the style and design of the machine tool in question, this value could be larger than the maximum turning diameter mentioned above, however this does NOT mean that you can turn a part larger than that specified in the maximum turning diameter specification.

Horsepower & Torque: Horsepower and torque are obvious considerations when purchasing a new machine, but their necessity may not be so obvious in all cases. If you are running work such as castings and forgings, drilling large diameter holes in steel, or generally turning features on large diameter parts, then horsepower and torque are going to be very important to you, and you should be certain that the machine in question has enough for your application. However, if you are more focused on high production or general turning of small to medium sized parts, then spindle RPM may become more important than power in your case.

Just as we have seen in the milling arena over the past several years, high-speed machining is quickly making its way into turning as well. As the technology of turning tooling is advancing, and through the tool coolant options are more prevalent, the principles of cutting shallower but faster are becoming more common. Spindle speed, rapid traverse, and maximum programmable feed rates become much more important than sheer horsepower and torque.

Maximum Turning Length: Very similar to the maximum turning diameter, this specification indicates the longest part that can be turned based on the mechanical limitations and axis travels of the machine tool. Keep in mind – the effective maximum turning length, for a particular part, can be less than specified by the use of larger or deeper chucks, or tooling that sticks out from the face of the turret farther than what is considered “normal”. In both cases you would be introducing the possibility for mechanical interferences – which would restrict the length of the part that could be machined, even though the physical travels and limits of the machine have not been changed.


Bed design 

Now let’s discuss the ins and outs of the two main bed designs – the true slant bed and the flatbed “flying wedge” configurations.

First we will dive into the true slant bed design. Unlike the flatbed flying wedge design – where the slant is achieved by the addition of a bolt-on wedge that is mounted on the cross slide – the true slant bed machine casting is manufactured with the slant built in. This not only offers more rigidity and thermal stability, but also proves to give the casting more overall mass, and means you have a much heavier machine with a smaller footprint. Typically the true slant bed design is offered in one of two slant angles, 30 degree and 45 degree, but there are also some 60 degree models available.

There are many advantages to the true slant bed design, and it is probably the most common configuration in modern CNC lathes. One of the most well-known and obvious advantages to the true slant bed is better chip evacuation. As the chips are created during the machining process, they are immediately washed down toward the chip bed by gravity and the normal flow of the coolant. This keeps chips from accumulating on flat surfaces, which not only helps control the chips in high volume production applications, but can also aid in prolonging the overall life of a machine – by reducing undue wear on the ways and other moving parts.

Another advantage to the true slant design is larger X-axis travels. Unlike the flatbed lathes where guide rail length is limited to the horizontal depth of the casting, the true slant bed design allows for longer X-axis rails. Just like in a square box, the straight sides of the box are one specific length, but the angular distance from one corner to the other is much longer. The same is true for the slant bed casting design which obviously means a larger part capacity in a smaller machine footprint. Although the flying wedge design, with the bolt-on slant, can also offer some increased X-axis travels over traditional flatbed machines, it can also magnify the lack of rigidity that is present in the bolt-on approach. You just cannot substitute for a sturdy casting design.


Thermal dynamics are also a big consideration in any machining process. The angular configuration of the base casting, and extended X-axis guideways, also offer better rigidity and part accuracies. Since the linear rails are longer, the base saddle casting that carries the turret can also be longer, providing a much sturdier base of support for the turret. And as the machine components begin to heat-up during the machining process, the headstock, tailstock and cross slide will all begin to grow along the same 30, 45, or 60 degree plane as the X-axis – unlike the flatbed flying wedge design, where the X-axis is mounted on a slant, but the rest of the machine components are mounted on the horizontal flatbed plane.

For more information, contact Hurco – Tel: (011) 849-5600.